Credit Spread Options Strategy: How to Pick Width and Strike for SPX
Trading Education ·
- What a Credit Spread Actually Does in SPX
- Choosing Your Short Strike: Start With Structure, Not Delta
- Spread Width: The Decision Most Traders Get Wrong
- Expiration Selection and 0DTE Considerations
- Position Sizing Within Your Account Tier
- Managing the Trade After Entry
- Putting the Framework Together
- Frequently Asked Questions
- Final Thought
A credit spread sounds straightforward: sell one option, buy another, collect the difference. But on SPX, the decisions that actually drive your results — which strike to sell, how wide to make the spread — are exactly where most retail traders either leave money on the table or absorb losses they never planned for.
This article walks through the practical mechanics of strike selection and spread width for SPX credit spreads, using supply and demand analysis as the structural anchor for those decisions. If you've been defaulting to delta alone or picking widths without a clear rationale, this framework gives you something more deliberate to work with.
What a Credit Spread Actually Does in SPX
A bull put spread or bear call spread on SPX collects premium upfront. Your maximum gain is that credit. Your maximum loss is the spread width minus the credit received. That ratio — how much you risk to collect how much — is the whole trade.
SPX has real structural advantages for this strategy. It's cash-settled, so early assignment isn't a concern. It's European-style, meaning exercise only happens at expiration. And the liquidity in SPX options is deep enough that bid-ask spreads on standard strikes stay tight, especially near the money.
None of that eliminates risk. It just removes some of the mechanical friction that trips up spread traders in thinner underlyings.
Choosing Your Short Strike: Start With Structure, Not Delta
The standard advice is to sell the 30-delta or 16-delta option. Delta is a useful reference point, but it's a probability description — not a reason to expect price to stop at a specific level.
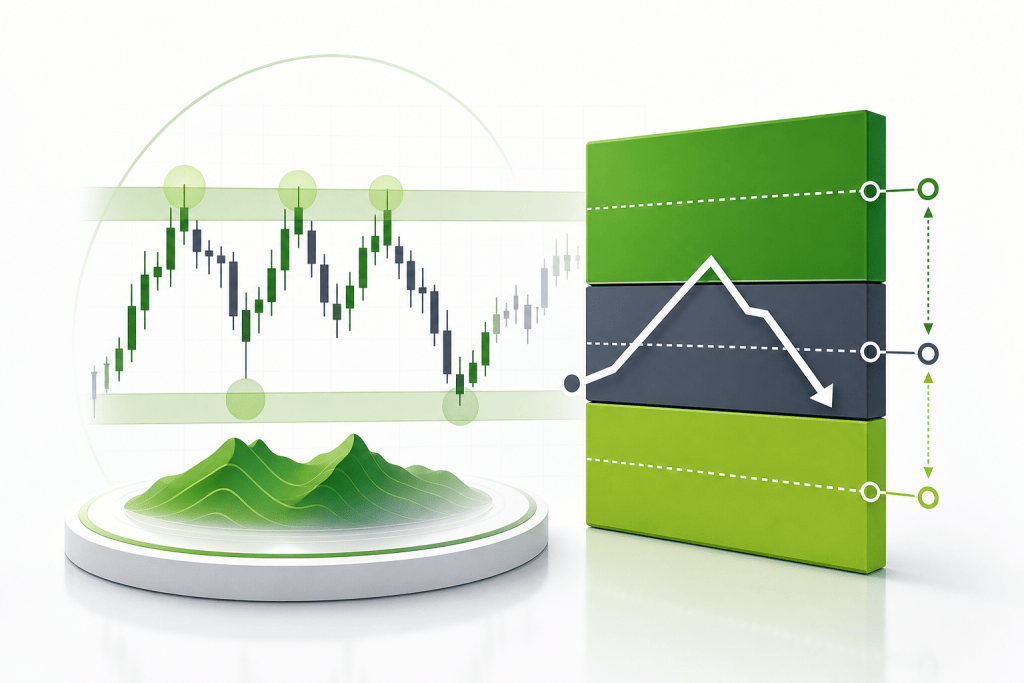
Supply and demand analysis gives you the structural reason. Before picking a strike, identify where institutional order flow has previously caused price to reverse: a supply zone above current price for a bear call spread, or a demand zone below for a bull put spread.
Here's why that distinction matters. If you sell a call spread with the short strike sitting inside an active supply zone, you have both the probability argument and the structural argument working together. If you sell at a delta level that sits in open air between zones, you're relying entirely on statistics with nothing underneath them.
How to Identify Usable Supply and Demand Zones on SPX
Supply zones on SPX typically form at prior swing highs where price dropped sharply and impulsively. The zone is defined by the base of that move — the last consolidation before the aggressive sell-off began.
Demand zones form at prior swing lows where price reversed quickly and moved up with momentum. Same principle: the base of the move defines the zone.
For 0DTE or same-week spreads, you're primarily working with intraday and recent daily structure. Zones from three to six weeks ago are often still relevant if they haven't been tested and broken. Zones from six months back are less reliable unless price has interacted with them multiple times.
Place your short strike at or just beyond the near edge of the zone — not inside it, not well past it. If price reaches your short strike, you want it entering a level where sellers (for calls) or buyers (for puts) have historically shown up.
Spread Width: The Decision Most Traders Get Wrong
Width sets your maximum loss and your capital requirement. Wider spreads collect more premium but demand more margin and expose you to larger losses. Narrower spreads cap your downside but often collect too little to justify the trade.
The right width isn't a fixed number. It depends on three things: where the next significant structural level sits beyond your short strike, how much premium the spread collects relative to its width, and how much of your account you're willing to put at risk.
The Structural Width Method
Once you've identified your short strike at a supply or demand zone, look at the next zone in the same direction. That's your natural boundary for the long strike.
Say you're selling a bear call spread and your short strike is at a supply zone around 5,800. If the next meaningful resistance level is near 5,830, a 25- to 30-point wide spread makes structural sense. The long strike at 5,825 or 5,830 lands near the next level where price might stall again.
If there's no meaningful structure within 30 points, that's information too. It may mean the zone isn't as clean as it looks, or that the market is in a range where spread structures are less favorable.
Credit-to-Width Ratio
A practical benchmark: aim to collect at least 25% to 30% of the spread width in premium. On a 25-point wide SPX spread, that means collecting $6.25 to $7.50 per share, or $625 to $750 per contract.
If a 25-point wide spread is only collecting $2.00 to $3.00, the risk-reward is poor. You're risking $22 to $23 to make $2 to $3. That math only holds if your win rate is extremely high — and no spread strategy sustains that consistently over time.
When premium is thin relative to width, you have two options: narrow the spread to reduce the risk amount, or move the short strike closer to the money to collect more premium. Moving closer increases the probability of the spread being tested, so that tradeoff needs to be made deliberately, not by default.
Expiration Selection and 0DTE Considerations
SPX now has daily expirations, which makes 0DTE spreads a distinct sub-strategy within the broader credit spread approach. The mechanics are the same, but time compression changes how you think about strike selection.
On a 0DTE spread, you're working with the current day's range and structure. The zones that matter are visible on the 15-minute and 30-minute charts — prior session highs and lows, overnight gaps, intraday consolidation bases.
The premium decay curve on 0DTE options is steep, which is why many traders favor them for credit spreads. Theta works aggressively in your favor once the trade is placed. But that same time compression means price moves can be fast and directional, especially around macro data releases. Placing 0DTE spreads on days with scheduled Fed commentary, CPI, or jobs data requires extra caution — structural zones can be overrun quickly when volatility expands.
For weekly or monthly expirations, you have more time for the trade to work, but you're also exposed to more cumulative price movement. Wider zones, more conservative strike placement, and tighter position sizing all become more important as expiration moves further out.
Position Sizing Within Your Account Tier
How wide you go and how many contracts you trade are directly tied to your account size. A 25-point wide SPX spread requires roughly $2,500 in margin per contract. On a $5,000 account, two contracts puts 100% of your capital at risk on a single trade — which isn't a viable approach regardless of how clean the setup looks.
A reasonable guideline is to risk no more than 2% to 5% of your account on any single credit spread position. On a $5,000 account, that's $100 to $250 per trade. On a $50,000 account, it's $1,000 to $2,500.
This is why account size segmentation matters in practice. The spread structures that make sense for a $5,000 account are genuinely different from those that make sense for a $100,000 account — not just in contract count, but in width, strike selection, and how much flexibility you have to manage a losing position.
At Blueville Capital, membership tiers are structured around portfolio size rather than feature bundles, which reflects this reality directly. The Base tier starts at a $5,000 minimum portfolio, while the Preferred tier is built for accounts at $100,000 or more. Daily index setups are delivered with the supply and demand reasoning included alongside the alert — not just a strike and expiration dropped into a chat with no context.
Managing the Trade After Entry
Credit spreads on SPX are not set-and-forget. Once you're in, you need a clear plan for three scenarios: the trade moves in your favor, it moves against you, or it sits near your short strike heading into expiration.
When the Trade Is Working
If the spread has collected 50% or more of its maximum profit and time remains, closing early is usually the better call. The remaining premium rarely justifies holding through the risk of a late-session reversal, particularly on 0DTE or same-week expirations. Locking in a realized gain at 50% of max profit is disciplined — not a missed opportunity.
When Price Approaches Your Short Strike
This is where supply and demand analysis earns its keep. If price is approaching your short strike and the zone is holding — rejection candles, volume tapering, price stalling — you may have reason to stay in. If price is slicing through the zone with momentum, the structural argument for the trade has failed and you should exit or roll.
Rolling means closing the current position and opening a new one at a different strike or expiration. Rolling for a credit — collecting more premium on the new position than you spend to close the old one — is the only version worth considering. Rolling for a debit to avoid a loss typically just delays and compounds the problem.
Hard Stop Rules
Define your maximum loss before you enter. A common approach is to close the spread if the position reaches two to three times the credit received as a loss. On a spread that collected $5.00, that means closing if the spread is trading at $10.00 to $15.00. One losing trade shouldn't wipe out several winners.
Putting the Framework Together
Selecting a credit spread on SPX isn't something you can fully reduce to a delta target and a fixed width. The decisions that matter — where to sell, how wide to go, when to exit — all benefit from structural context that pure probability models don't provide.
Supply and demand zones give you a reason to place the short strike where you do, not just a statistical argument. Width should reflect the distance to the next meaningful structural level and the premium collected relative to the risk. Position sizing should reflect your actual account, not an arbitrary contract count.
If you want to see how this methodology applies to live SPX setups with the reasoning made explicit, the trade performance log at Blueville Capital covers index spread trades with the context behind each position — the kind of transparency that lets you evaluate a methodology rather than just take someone's word for it.
Frequently Asked Questions
What is a credit spread options strategy on SPX?
A credit spread on SPX involves selling one option and buying another at a different strike within the same expiration, collecting the net premium as income. The maximum gain is the credit received; the maximum loss is the spread width minus that credit. SPX's cash-settled, European-style structure makes it a common choice for this strategy among retail traders.
How do I choose the right strike for a credit spread on SPX?
Start by identifying supply zones (for bear call spreads) or demand zones (for bull put spreads) using recent price structure on the SPX chart. Place your short strike at or just beyond the near edge of that zone so the structural and probability arguments are both working in your favor. Avoid placing strikes in open air between zones where there's no historical reason for price to stall.
What spread width should I use for SPX credit spreads?
Width depends on the distance to the next structural level beyond your short strike, the premium collected relative to the risk, and your account size. A general benchmark is to collect at least 25% to 30% of the spread width in premium. On a 25-point wide spread, that means collecting $6.25 or more per share per contract.
Are 0DTE credit spreads on SPX riskier than weekly spreads?
0DTE spreads benefit from aggressive theta decay but are more sensitive to fast directional moves, particularly around scheduled macro events. They require tighter intraday zone analysis and clear exit rules. Weekly spreads give the trade more time to work but expose you to more cumulative price movement. Neither is inherently riskier — it depends on how the position is sized and managed.
How much should I risk per credit spread trade?
A common guideline is 2% to 5% of your account per trade. On a $5,000 account, that's $100 to $250 at risk. On a $50,000 account, it's $1,000 to $2,500. SPX spreads require meaningful margin per contract, so account size directly affects how many contracts you can trade responsibly.
When should I close a credit spread early?
Closing at 50% of maximum profit is a widely used rule and often the right call, particularly on 0DTE or same-week expirations. The remaining premium rarely justifies holding through late-session volatility. If price is approaching your short strike and the structural zone is failing, exit before the spread reaches your maximum loss.
What is the role of supply and demand analysis in credit spread selection?
Supply and demand analysis identifies price levels where institutional order flow has historically caused reversals. Placing your short strike at these levels gives you a structural reason — not just a statistical one — to expect price to stall there. This is the core methodology behind Blueville Capital's daily index spread setups on SPX, RUT, SPY, and IWM.
Final Thought
A credit spread is only as good as the reasoning behind the strike and width selection. Delta tells you the probability. Structure tells you why. When both point in the same direction, you have a trade worth taking. When they conflict, you have a reason to wait.
If you want daily SPX setups built on this kind of structured analysis, Blueville Capital delivers trade setups with the supply and demand reasoning included — not just the ticker and strike.


