How to Combine Supply and Demand with Options Greeks for Better Trade Timing
Trading Education ·
- Why Neither Framework Is Enough on Its Own
- Start With the Zone—Always
- How Delta Fits Zone-Based Entries
- Theta Is the Cost of Being Early
- Vega and the Volatility Context Around Zones
- Gamma and the Timing of Zone Reactions
- Building the Full Framework: A Practical Sequence
- Applying This to Index Options Specifically
- Common Mistakes When Combining These Frameworks
- FAQs
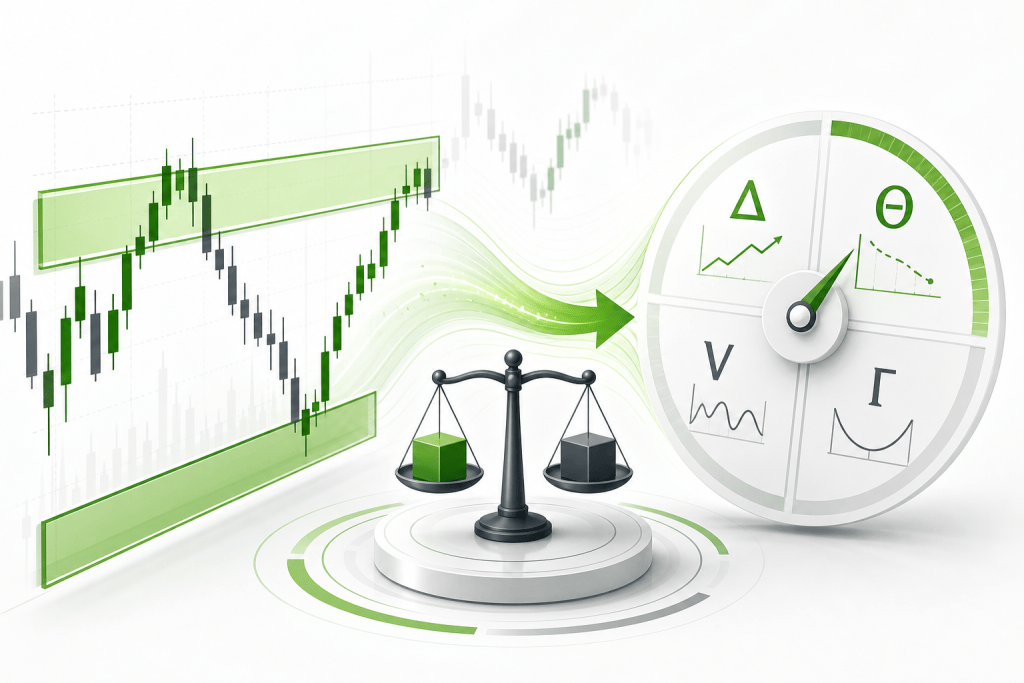
Supply and demand zones tell you where price is likely to react. Options Greeks tell you how your position will behave when it does. Used separately, each framework has real blind spots. Together, they give you a timing and sizing edge that neither delivers on its own.
If you've ever placed a trade at a textbook demand zone only to watch price grind sideways while theta bleeds you out—or bought calls with high delta right before implied volatility collapsed—this is the article that fills those gaps.
Why Neither Framework Is Enough on Its Own
Supply and demand analysis identifies institutional price levels where buying or selling pressure has historically overwhelmed the other side. When price revisits a strong demand zone, the probability of a bounce increases. But that tells you nothing about whether your option is fairly priced, how fast it's losing value, or whether a volatility crush will erase a directional gain you were right about.
Greeks, on the other hand, describe your option's sensitivity to price movement, time, and volatility with precision. Delta gives you directional exposure. Theta tells you what you're losing each day just by holding. Vega shows how much your position gains or loses as implied volatility shifts. Gamma tells you how fast delta itself is changing. These are exact measurements—but they don't tell you where price is going or when a move is likely to start.
The combination closes both gaps. A supply or demand zone gives you the location and the directional thesis. The Greeks help you build a position that can survive the time it takes for that thesis to play out.
Start With the Zone—Always
The entry point for this framework is the price chart, not the options chain. Before you look at a single Greek, you need a clearly defined supply or demand zone with at least one of the following:
- A sharp, impulsive move away from the level on the initial departure
- A fresh zone that price hasn't revisited since forming
- Confluence with a broader structural level on SPX, SPY, RUT, or IWM
Once you have a zone you trust, you have your directional bias and a rough sense of where price should react. That's when the Greeks become useful.
How Delta Fits Zone-Based Entries
Delta measures how much your option's price moves for every one-point move in the underlying. A call with a 0.50 delta gains roughly $0.50 for every $1.00 SPX moves in your favor.
When you're entering at a demand zone expecting a bounce, you want enough delta to capture the move without overpaying for deep in-the-money options. A practical target is calls or call spreads with a delta between 0.40 and 0.60 at entry—close to at-the-money, where directional sensitivity is meaningful but premium cost stays reasonable.
At supply zones, the same logic applies in reverse. Puts or put spreads in the 0.40 to 0.60 delta range give you clean exposure to an anticipated rejection and move lower.
One thing worth keeping in mind: delta also approximates the probability that an option expires in the money. A 0.50 delta option is roughly a coin flip at expiration. That framing matters when you're deciding between a single long option and a spread.
Theta Is the Cost of Being Early
This is where most zone traders get hurt. You identify a solid demand zone, enter a long call, and price consolidates for two days before finally bouncing. By the time the move happens, theta has eaten a significant chunk of your premium—even though you were right.
Theta decay accelerates as expiration approaches, especially inside the final week. If you're trading weekly options on SPX or SPY and entering at a zone that might take two or three days to resolve, you're fighting time decay from the moment you put the trade on.
Two practical solutions. First, use a spread instead of a naked long option. A debit spread reduces theta exposure because the short leg partially offsets the decay on the long leg. If the zone holds and price moves your way, the spread still captures most of the directional gain while bleeding less premium while you wait.
Second, give yourself more time. Entering with 10 to 14 days until expiration rather than 3 to 5 gives the zone room to work without theta destroying the position. This matters most on swing setups where you're planning to hold more than one session.
Vega and the Volatility Context Around Zones
Implied volatility is the market's expectation of future price movement, and vega measures how much your option's price changes when IV shifts by one percentage point.
This creates a specific risk that zone traders often miss. When price approaches a major supply or demand zone, implied volatility frequently rises because the market is pricing in uncertainty about the outcome. If you buy a call at a demand zone when IV is already elevated, you're paying a premium for that uncertainty. If the zone holds and price bounces but IV collapses back to normal, your option can actually lose value—even though you were directionally correct.
The fix is straightforward: know where IV stands relative to its recent range before you enter. If IV is elevated at your zone entry, a spread structure helps because the short leg also benefits from a volatility crush, partially offsetting the vega loss on the long leg.
Flip that around—if IV is compressed when you enter near a zone, long options become more attractive. A move from the zone is likely to bring an IV expansion that adds to your directional gain rather than working against it.
Gamma and the Timing of Zone Reactions
Gamma measures the rate of change of delta. When gamma is high, a small move in the underlying causes a large shift in your delta—and this matters most for short-dated options.
Near a supply or demand zone, gamma can work strongly in your favor if you time the entry well. If price tags a demand zone and begins to bounce, a short-dated call with high gamma will see its delta increase rapidly as price moves away from the level. That acceleration means your position gains value faster than a longer-dated option would on the same move.
This is why many index options traders use 0DTE or 1DTE options specifically at high-conviction zones. The gamma is extreme, so a clean zone reaction produces outsized gains quickly. The risk is equally extreme if the zone fails—which is why position sizing matters as much as setup quality.
Building the Full Framework: A Practical Sequence
Here's how to apply this in order on a real trade:
1. Mark your zones. Identify a fresh supply or demand zone on SPX, RUT, SPY, or IWM. Confirm zone quality: impulsive departure, fresh level, structural confluence.
2. Define your directional bias. Demand zone means bullish bias—calls or call spreads. Supply zone means bearish bias—puts or put spreads.
3. Check the IV environment. Is implied volatility elevated or compressed relative to its recent range? Elevated IV favors spreads. Compressed IV makes long options more attractive.
4. Choose your expiration based on expected holding time. If you expect a same-day reaction, 0DTE or 1DTE options with high gamma can work well. If the setup may take two to four days to resolve, use 10 to 14 DTE to reduce theta risk.
5. Select your strike using delta. Target the 0.40 to 0.60 delta range for directional plays. This keeps you near at-the-money with meaningful sensitivity to the anticipated move.
6. Decide between a long option and a spread. If theta and vega risk are concerns, a debit spread reduces both. If IV is low and you want maximum upside from a clean zone reaction, a single long option captures more of the move.
7. Set your invalidation level. Define the price where the zone is broken. If price closes through your demand zone rather than bouncing, the thesis is wrong. Your exit should be tied to that level—not an arbitrary percentage loss.
Applying This to Index Options Specifically
SPX, RUT, SPY, and IWM each have their own liquidity and spread characteristics, but the framework applies across all four. SPX and SPY tend to have tighter bid-ask spreads on near-the-money options, making them more cost-efficient for the spread structures described above. RUT and IWM can show sharper zone reactions because the small-cap index is more sensitive to risk-on and risk-off flows.
For 0DTE setups, the gamma dynamic is most pronounced on SPX, which has Monday, Wednesday, and Friday expirations. A high-conviction demand zone on SPX combined with compressed IV and a clean price rejection is the scenario where gamma acceleration works hardest in your favor.
At Blueville Capital, the daily index trade setups on SPX, RUT, SPY, and IWM are built around supply and demand zone analysis with a stated goal of 50%+ profit per play. Understanding how Greeks interact with those zones is what separates traders who apply the setups consistently from those who take the same signal and get different results based on how they structured the position.
Common Mistakes When Combining These Frameworks
Ignoring theta on multi-day setups. Entering a weekly option with three days left on a zone that needs time to resolve is a reliable way to be right directionally and still lose money.
Buying high-vega options into an IV spike. If the market is already pricing in a large move, you're paying for that expectation upfront. A spread neutralizes some of that vega exposure.
Treating delta as fixed. Delta changes as price moves and as time passes. A 0.50 delta option at entry might be a 0.30 delta option two days later if price drifts away from your strike. Gamma is the reason delta isn't static, and understanding that helps you manage positions—not just entries.
Over-relying on the zone without checking the Greeks. A perfect zone setup with poor option structure is still a poor trade. Both inputs matter every time.
FAQs
What is the best delta range for options entries at supply and demand zones?
For directional plays at supply or demand zones, the 0.40 to 0.60 delta range is a practical starting point. It puts you near at-the-money with meaningful directional sensitivity and without the premium cost of deep in-the-money options. The exact delta depends on your expected holding time and whether you're using a single option or a spread.
How does theta affect zone-based options trades?
Theta is the daily cost of holding an option. If price consolidates at a zone for several days before reacting, theta erodes your premium even when your directional thesis is correct. Using debit spreads or choosing expirations with 10 to 14 days remaining helps reduce this drag on multi-day setups.
Should I use long options or spreads at supply and demand zones?
It depends on the IV environment and your expected holding time. When implied volatility is elevated, spreads are generally more efficient because the short leg offsets vega risk. When IV is compressed and you expect a sharp same-day reaction, a long option captures more of the directional gain.
What role does vega play when entering at a high-conviction zone?
Vega measures your exposure to changes in implied volatility. If IV is high when you enter, a zone reaction that also brings an IV collapse can reduce your option's value even on a winning directional move. Spreads reduce this risk through the short vega component on the short leg, which partially offsets the long vega exposure.
Why is gamma especially important for 0DTE zone trades?
Gamma is highest for short-dated options close to at-the-money. In a 0DTE setup, a clean zone reaction causes delta to accelerate rapidly, meaning your position gains value faster than a longer-dated option would on the same move. That amplification works in both directions, so position sizing and a clear invalidation level are non-negotiable.
Can this framework be applied to RUT and IWM as well as SPX?
Yes. The supply and demand plus Greeks framework applies to any liquid index options market. RUT and IWM can show sharper zone reactions due to small-cap sensitivity to risk appetite, while SPX and SPY typically offer tighter spreads and more efficient option pricing for the spread structures in this framework.
How do I know when a supply or demand zone has failed?
A zone is typically invalidated when price closes through it rather than bouncing. Define your invalidation level before entry, tied to the zone boundary, and exit when price closes beyond that level. Waiting for a close rather than reacting to an intraday wick reduces the chance of getting stopped out by noise.
Supply and demand zones give you the map. Options Greeks give you the vehicle suited to the terrain. Used together, they let you enter with a clear thesis, structure a position that can survive the wait, and exit with a defined reason rather than a gut feeling. If you want to see how this methodology is applied to daily SPX, RUT, SPY, and IWM setups in practice, explore what's available at Blueville Capital.


